What are the common closing costs for a home buyer in Utah?
Most Utah home buyers pay about 1.5% to 3% of the purchase price in closing costs (roughly $9,000 to $18,000 on a $600,000 home) on top of the down payment. The biggest expenses contributing to closing costs are lender fees, the appraisal, the lender's title insurance policy, your escrow fee, and prepaid property taxes, homeowners insurance, and interest. Utah has no real estate transfer tax, and under the standard Utah REPC the seller pays for your owner's title insurance policy. HOA communities like Daybreak can add additional fees at closing.
Here's the number that surprises many first-time home buyers: there’s more required than just your down payment. Closing costs are a separate pile of fees, and they can add up to be a surprising number.
The good news? Utah is one of the cheaper states to close in. There's no transfer tax, the seller customarily buys your owner's title policy, and a lot of these costs are negotiable if you know where to push.
This is one of the most common questions we get from buyers across Salt Lake County and Utah County, so here's exactly what you'll pay, why, and how to bring the number down.
The Closing Costs Every Utah Buyer Should Expect
Your costs fall into four buckets: what your lender charges, what third parties charge, what you prepay, and what your HOA charges (if you have one).
1. Lender fees
This is usually the biggest variable, and the one you have the most control over.
Origination and underwriting fees: Often around 0.75% of the loan amount, or a flat $1,500–$4,000 depending on the lender
Discount points (optional): One point equals 1% of your loan and buys down your interest rate. On a $540,000 loan, that's $5,400.
Credit report, flood certification, and processing fees: Usually bundled into the lender's fee sheet
Two lenders can quote the same rate with wildly different fees. Always compare the Loan Estimate side by side, specifically Section A (origination charges).
2. Third-party fees
These are services your lender requires or you choose to buy.
Appraisal: $600-$900
Lender's title insurance policy: Roughly $450-$600 on a $500,000-$600,000 loan when it's issued alongside the seller-paid owner's policy
Escrow/closing fee: Under the Utah REPC (Section 4.3), you and the seller each pay your own share of the title company's escrow fee- typically a few hundred dollars per side
Recording fees: About $45 per document in Utah, roughly $90 for a standard purchase (deed plus deed of trust)
Home inspection: $400-$700, plus $150-$600 for any specialty inspections (radon, sewer scope, roof). You'll pay these during your due diligence period, before closing, but budget for them now.
3. Prepaids and escrow reserves
This is the part buyers forget. Prepaids aren't fees, they're your own future bills paid up front, and they can easily run $3,000-$6,000.
Property tax reserves: Your lender collects several months of property taxes to seed your escrow account. Utah's effective property tax rate runs roughly 0.55%-0.85% a year, so a $600,000 home might carry about $3,300-$4,000 in annual taxes.
Homeowners insurance: Your first year's premium is typically paid at or before closing, plus a couple of months in reserve.
Prepaid interest: Interest from your closing date to the end of that month. Close on the 28th and it's a few days' worth. Close on the 3rd and it's nearly a full month.
Prorated property taxes and HOA dues: Under Section 4.1 of the REPC, taxes and dues are split as of the settlement date, so you may owe or receive a credit depending on what the seller has already paid.
4. HOA fees at closing
If you're buying in an HOA community (like Daybreak) expect a few extra line items:
Change-of-ownership fee (sometimes called a reinvestment or community enhancement fee): Daybreak's is roughly 0.5% of the sale price, or about $3,000 on a $600,000 home
HOA payoff/statement fee: Usually a few hundred dollars or less
First month or quarter of dues
Here's the key: Section 4.3(c) of the Utah REPC has a checkbox for who pays the change-of-ownership fee, buyer, seller, or split. It's negotiable, and on a $3,000 line item that checkbox matters. If you're weighing a Daybreak home, our breakdown of Daybreak HOA fees and what buyers need to know walks through the monthly side of the equation.
What It Actually Looks Like on a $600,000 Home
Let's run a real-world example. Say you're buying a $600,000 home in South Jordan with 10% down and a $540,000 conventional loan, closing mid-month.
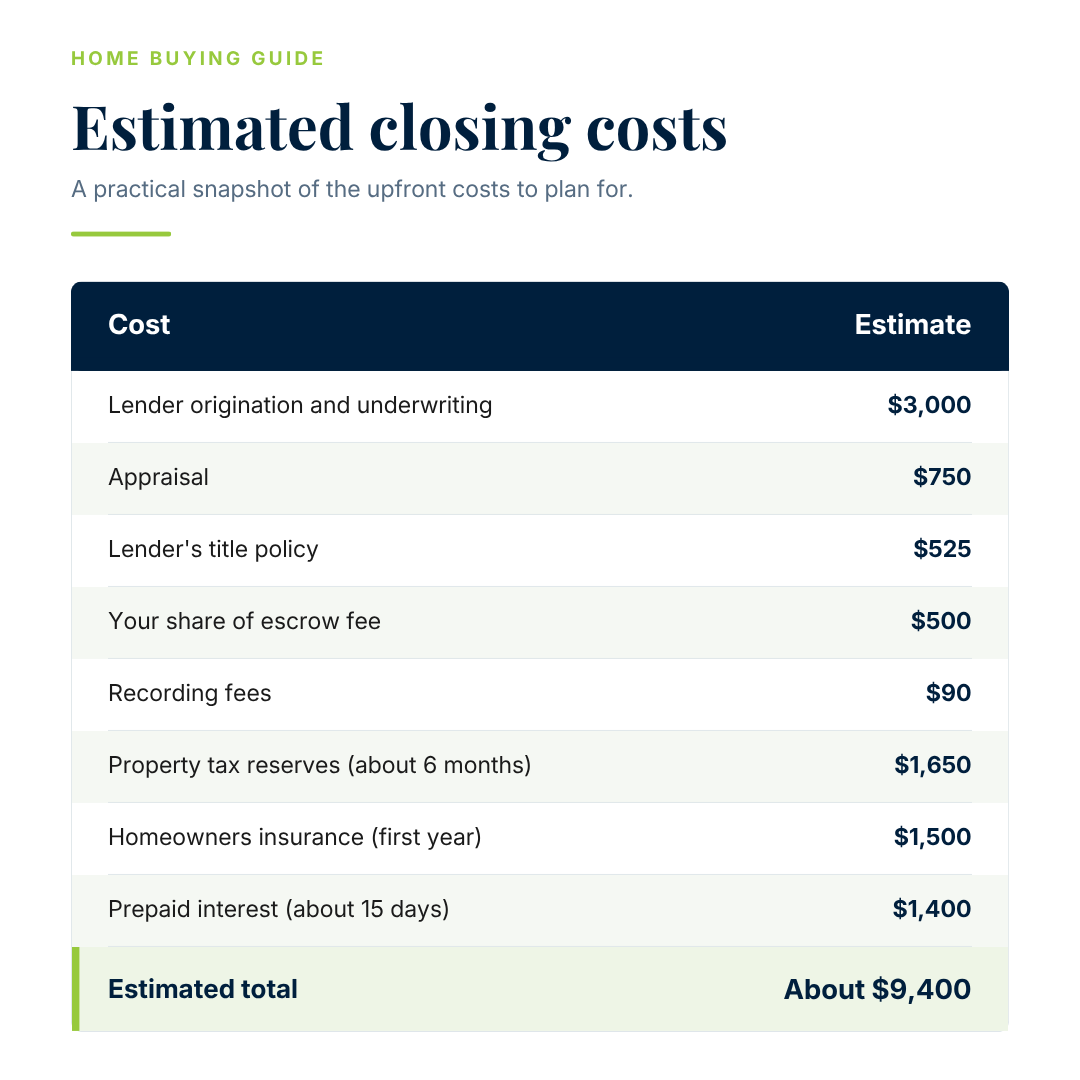
Add a Daybreak change-of-ownership fee and you're closer to $12,400. Buy one discount point and you're pushing $18,000.
That's why we tell buyers: the "2–3%" rule of thumb is a starting point, not a quote. Your real number depends on your loan type, your lender, your closing date, and the specific community you're buying in.
What you won't pay in Utah
No transfer tax. Many states charge 1% or more to record a sale, while Utah doesn’t.
No owner's title policy (usually). Section 6.2 of the Utah REPC puts the owner's policy on the seller. On a $600,000 home, that's roughly $1,375–$1,700 you don't have to cover.
No attorney closing fee. Utah closings run through a title company, not an attorney.
How to Lower Your Closing Costs
You have a little more leverage here than buyers might realize.
Ask for seller concessions. You can negotiate for the seller to cover part of your closing costs in the REPC. Conventional loans generally allow 3% in seller concessions with less than 10% down and 6% with 10–25% down; FHA allows up to 6%. In a balanced market, this is one of the most common asks we write into offers.
Negotiate the HOA change-of-ownership fee. That REPC checkbox is fair game.
Shop at least two or three lenders. Compare Loan Estimates on the same day, for the same loan type, with the same number of points.
Pick your closing date strategically. Closing near the end of the month reduces prepaid interest at the table (though it doesn't change your total cost of the loan).
Ask about lender credits. Some lenders will cover part of your closing costs in exchange for a slightly higher rate, this can be useful if cash is tight today.
The right mix depends on how long you plan to stay in the home, how competitive the listing is, and how much cash you want to keep in reserve after you move in.
Frequently Asked Questions
How much are closing costs for a buyer in Utah?
Utah buyers typically pay 1.5% to 3% of the purchase price in closing costs, or roughly $9,000 to $18,000 on a $600,000 home. The total depends on loan type, lender fees, discount points, prepaid taxes and insurance, and any HOA change-of-ownership fee.
Who pays for title insurance in Utah?
Under the standard Utah REPC, the seller pays for the buyer's owner's title insurance policy. The buyer pays for the lender's title policy, which is usually a few hundred dollars when issued together with the owner's policy.
Does Utah have a real estate transfer tax?
No. Utah does not charge a state or local real estate transfer tax, which makes closing in Utah less expensive than in many other states. You'll still pay small county recording fees, about $45 per document.
Who pays the Daybreak HOA transfer fee at closing?
Daybreak charges a one-time change-of-ownership fee of roughly 0.5% of the sale price at closing. Who pays it is negotiable (Section 4.3(c) of the Utah REPC lets you assign it to the buyer, the seller, or split it equally).
Can the seller pay my closing costs in Utah?
Yes. You can negotiate seller concessions in the REPC to cover some or all of your closing costs, within your loan program's limits. Conventional loans generally cap concessions at 3%-6% depending on your down payment, and FHA allows up to 6%.
Ready to Know Your Real Number?
Closing costs in Utah are lower than in most states, but they're still real money, and the difference between a well-negotiated offer and a rushed one can be thousands of dollars. The fastest way to know what you'll actually bring to the table is to run your numbers with someone you trust.
Whether you're just starting to look in South Jordan, shuffling to a new village in Daybreak, or stepping into your next home in Utah County, the Zander Team will help you build an offer that protects your cash. Reach out anytime at 801-446-2662. We'd love to be your guide.
Figures are estimates for general information as of September 2026 and aren't a loan quote. Confirm exact costs with your lender and title company.